U.S. Bank offered a Smartly Visa card with great rewards in late 2024. They soon regretted it and pulled back the offer in April 2025. Some of us got in early and were grandfathered into the original terms with only minor modifications. If you didn’t get in early, it’s still a good card, but it’s not necessarily the best.
This isn’t a sponsored post. It contains no affiliate links. I have no relationship with any bank or broker except as a customer.
4% Rewards
The grandfathered customers receive 4% cash-back rewards on everything when they also hold $100,000 in investments in a U.S. Bankcorp Advisors account. The 4% cash-back is capped on $10,000 in net charges per statement cycle, except for taxes, education, gift cards, insurance, and business-to-business transactions.
I like this card because it’s simple after a one-time setup. I get good rewards on every purchase, and there’s no annual fee or special categories to remember and juggle. The $10,000 cap per statement cycle is high enough that I’ve never run into it. Charges in the exception categories don’t count toward the $10,000 cap, and they still earn 2% rewards.
New customers earn 4% rewards only if they hold $100,000 in a U.S. Bank checking or safe debit account, which makes it not worth it. It’s still a plain 2% rewards card with no other requirements.
Other 2% Cash-Back Cards
If you didn’t get in early and you prefer to use one card for everything, only a handful of cards from other banks offer straight 2% cash-back rewards with no special categories.
Fidelity Rewards Visa is run by a division of U.S. Bank. It has better ancillary benefits than the U.S. Bank Smartly card, but it requires a Fidelity account for the 2% cash back.
Citi Double Cash card is a Mastercard. So is Synchrony Premier World card. These 2% rewards cards aren’t accepted at Costco.
Wells Fargo Active Cash card is similar to the U.S. Bank Smartly card.
What Works Well
The 4% credit card rewards are straightforward after a one-time setup. I qualified for the maximum 4% rewards only a few days after a brokerage account transfer brought the combined balances above $100,000. For instance, this $15 transaction earned 4% in reward points:
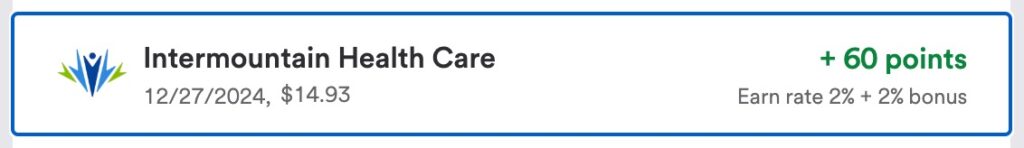
One reward point is worth $0.01 when you redeem it into a U.S. Bank checking or savings account (minimum 2,500 points = $25 per redemption). You can make a payment to the credit card from the checking or savings account.
Nice Card Design
The Smartly Visa card looks and feels premium in the hand because it’s black and metal. It doesn’t matter much though when you use Apple Pay or Google Pay.
Website and Mobile App
The U.S. Bank online banking website and mobile app work well. It was easy to set up paperless statements for all accounts and autopay for the credit card, change the PIN on the cards, and lock the debit cards.
The website supports logging in with a passkey. The mobile app supports biometric login with Face ID or fingerprint.
Transactions display nicely in online banking and the mobile app. You can download the credit card transactions in CSV or QFX format to import into personal finance software such as Quicken.
Bank of America shows this for a purchase at a Walmart:

U.S. Bank shows this:
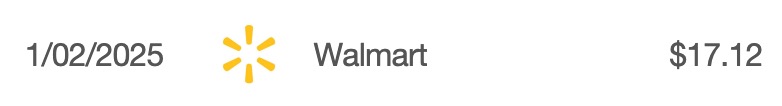
U.S. Bank translated the description “WM SUPERCENTER #4696” into a more recognizable merchant name “Walmart” with a logo. This adds a nice touch. I haven’t seen other banks doing it.
Brokerage Account
U.S. Bank’s brokerage service doesn’t advertise itself independently. Every brokerage customer is assumed to be a bank customer. You log in to the bank’s website to access the brokerage account. You use the same mobile app for both.
The brokerage account is handled by Fidelity behind the scenes. I’m holding one ETF worth a little over $100,000, which pays about $500 in dividends per quarter. I transfer the dividends to the savings account and make a payment to the credit card.
New customers don’t need the brokerage account to earn 2% rewards.
The Downsides
This setup with U.S. Bank has some downsides that don’t bother me.
Foreign Transaction Fee
The Smartly Visa card has a 3% foreign transaction fee. You still net 1% after the fee. You can use a different card for foreign transactions, but the no-fee card has to pay more than 1% on those purchases to make a difference. If you spend $5,000/year on foreign transactions, using a 2% card with no foreign transaction fee only nets you $50.
I’m inclined to just eat the 3% fee and not bother switching because I don’t spend that much on foreign transactions.
Skimpy Card Benefits
Although the card looks and feels premium physically, it comes with few ancillary benefits. It doesn’t have extended warranty or secondary rental car insurance. My old Bank of America card had those benefits, but I hadn’t had any chance to use them over 10+ years. If extended warranty or secondary rental car insurance is important to you, you must remember to use a different card on transactions you want to cover.
No FICO Score
Bank of America shows a FICO 8 credit score from TransUnion monthly at no charge if you opt in. U.S. Bank also offers a free credit score weekly, but it’s based on the VantageScore 3.0 model, which fewer lenders use. Seeing a FICO score is nice but not essential to me.
Only Email or SMS for 2FA
U.S. Bank’s website uses a passkey as an alternative to your password. The two-factor authentication only uses email or SMS. It doesn’t accept a Google Voice number for SMS. You must make sure to secure your email and mobile number. I activated the extra security feature offered by my mobile carrier to protect against unauthorized porting-out requests.
Low ACH Limits
The maximum amount of ACH push I can initiate at U.S. Bank is $1,500 per day and $3,000 per week. The low limits don’t affect me because I don’t need to transfer any money out. I’ll use the monthly credit card rewards and the quarterly dividends to pay toward the credit card.
Designating Beneficiaries Requires a Form
Designating beneficiaries for the brokerage account requires mailing a paper form or calling customer service to arrange for e-signing. It doesn’t bother me because it’s only a one-time task.
***
I’m on autopilot earning 4% rewards now. My activities in all U.S. Bank accounts come down to:
- Use the credit card for all purchases.
- U.S. Bank debits an external account on autopay (monthly).
- Redeem rewards into the savings account (monthly).
- Transfer the rewards deposit from the savings account to the credit card as a payment.
- Receive dividends in the brokerage account (quarterly).
- Transfer the dividends from the brokerage account to the savings account and make a payment to the credit card.
- Deposit paper checks to the checking account (rare).
- Transfer from the checking account to the credit card as a payment.
All money generated in the accounts stays within U.S. Bank. There won’t be any transfers to or from an external account except for autopay.
If you didn’t get in before April 2025, this card is still a plain 2% rewards card with no annual fee, no special categories, and no caps. Not many cards from other banks offer 2% rewards on everything. You’d have to juggle multiple cards for rewards higher than 2%.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.
David says
I, and many others, received a $500 credit limit. I was able to call after a couple days and request an increase (with a desired limit), which was manually reviewed and approved a day later. Unfortunately this results in a 2nd hard pull.
Steve J says
Can you explain the second hard pull? Thanks
Harry Sit says
A manual review to approve an application denied by the automated system or to increase the credit limit assigned by the automated system requires a new inquiry to your credit report, which will be recorded by the credit bureau as a second hard pull subsequent to the first hard pull by the automated system.
Jamie says
I did the CL increase online and I was denied. And then I called and they said they can’t try again for 6 months.
So I’m at $500 max for six months.
Dan says
Checking account routinely has promotions paying out $450+ for opening and direct deposits. There is this promotion now.
Harry Sit says
The last $450 checking account bonus expired on 12/30/2024. I haven’t seen a new one coming out. Do you see it somewhere?
Zhen says
Thanks for the detailed information. Very helpful! I walked into a local US Bank branch today and got $450 promotion for checking account. The bank employee handed me a flyer showing the promotion runs from Jan 7 through April 17, 2025.
Harry Sit says
Thank you for the heads up on the new checking account bonus promotion. It’s also on the bank’s website now. I added the link to the post.
Paul says
Appreciate the detailed write up. Confirmed a few deal breakers for me so I don’t have to apply. Thanks!
Russ says
Thank you for the thorough write-up. It’s a good deal, but, wow, all those issues you ran into do not inspire confidence. I’ll be sticking with B of A’s 5.25% for online shopping and 2.625% for everything else.
TJ says
You don’t want to keep your BofA/Merrill around for a while just in case US Bank nerfs this product? They have been dropping the rate on the savings account, but so far haven’t touched the credit card.
I actually am shifting all my auto-pays to come out of the US Bank Smartly Savings instead of Alliant. 3.44% is good enough and certainly better than 0.25%. I could use Fidelity but I guess I feel more comfortable using an actual bank after so many people had some issues with Fidelity.
Harry Sit says
I’m hopeful this will go for another 10 years. I don’t want to keep brokerage accounts at three places.
People had issues with Fidelity only because they didn’t know they should make all deposits by push. Just this one small behavior change avoids all the problems.
TJ says
True, and you can always just apply for the other stuff again in the future if this one doesn’t last as long and the other one does.
S&Pat says
Harry, on Fido, what kind of deposits are they (deposit from Fido, or deposit to Fido?) that we need to do a “push” in order to prevent problems? Thanks.
Harry Sit says
Deposit to Fidelity. In general, do all transfers with a “push” by initiating the transfer at the place where the money currently resides. If the money is currently in bank A going to bank B, ask A to transfer it to B. It’s more natural that way and it avoids all the problems.
S&Pat says
Harry, Thanks for the explanation on “push”. Now we know.
SFGiants says
I was just denied for the card and I have an 850+ FICO score. I guess I’ll see what reason they provide in 7-10 days by mail.
TJ says
You can product change an existing US Bank card to the Smartly. It’s actually better as other US Bank cards have sign up bonuses, so whatever you are converting you could just apply again in the future presumably.
This also avoids the joke $500 limits that people are getting.
SFGiants says
I guess there was an issue validating my personal information. I’ve been approved after speaking with a representative.
Eric Schoellkopf says
I also moved assets to US Bank after reading about it from the Frugal Professor. I highly recommend signing up for his monthly blog posts. He is a frugal beast.
Matt says
I was checking my US Bank Credit card and literally just saw that this exists yesterday! Thanks for writing about it!
indexfundfan says
TIP: If you put in your ACH transfer requests from the brokerage side, the limits are much higher.
D says
Hello, we each have to open our own saving account and only one joint investment for $100k+?
Harry Sit says
The savings account can be a joint account. Both owners must complete the application. The bank can approve both, decline both, or approve one and deny the other.
Sharon says
Hi Harry, Met you briefly at the end of the Bogleheads Conference, when I came to ask you a question. I’ve read your posts for years and am always interested in your thoughts. Thanks for publishing this detailed post. For me, I don’t think getting the card would pass my “making fewer things matter . . . cutting a pineapple” test. Instead, I believe it would make it harder for my heirs to wrap up my estate (one more bank and brokerage to deal with). But I hope the card works for you and your wife.
Harry Sit says
It’s a lateral move for us when we already use Bank of America/Merrill Edge. Those accounts will be closed after we transition over. The number of places to deal with stays the same.
N says
How are you planning to make sure the balance stays above $100,000? Is the ETF you are using something low-volatility, or are you putting well above the minimum as a cushion?
Harry Sit says
The ETF has an 8% cushion right now. It’ll go below $100k if the price goes back to its 52-week low. I’m planning to push in additional cash to buy GABXX if I expect the dip to be short-lived. I’ll transfer additional shares if the price doesn’t recover quickly.
Lori says
Was the lack of fee on the VUSXX purchase acknowledged feature of the brokerage account or a beneficial fluke?
Harry Sit says
I don’t know. GABXX is just as good if you don’t trust that VUSXX will stay free of fees.
Lori says
Can treasury bills/notes be purchased from the brokerage account?
Harry Sit says
I don’t see any online interface to trade fixed income instruments. You can probably call and pay a fee to have someone trade them for you. The best way to use the brokerage account is to just hold some shares and never trade. If you must trade in this account, do it through ETFs such as SGOV, BIL, etc.
Lori says
Last year I moved my taxable investment assets out of Vanguard except for VUSXX. If I’m understanding the July 2024 account closure and transfer fee change correctly, I may be charged $100 if I transfer my remaining VUSXX holdings to US Bancorp (or close my account), but being a money market fund, I can get around this by selling, transferring the cash and repurchasing VUSXX or GABXX. I’ll lose a few days for the funds to settle and transfer, but that’s about it in terms of downsides that I see. Are there any I missed?
Harry Sit says
You will have to ask Vanguard whether they charge the fee if you sell the money market fund and close the account.
SFGiantsFan says
Has anyone sold GABXX yet? I see a $5 redemption fee in their prospectus.
Harry Sit says
I haven’t sold any from GABXX but I have read someone saying no fee was charged when he or she sold.
Mike says
I’m going to give this a try. Hopefully it will go well. I called and checked but they don’t have offices in Florida so I guess I have to either do it online or on the phone. which do you recommend?
Harry Sit says
It’s more convenient to do it online but I think you’ll have better success on the phone if you don’t mind calling. Online works if everything goes well but you only have one shot. If something doesn’t go through while you’re on the phone, the agent may be able to resubmit in a different way.
Mighty Investor says
Thanks for this post, Harry. 4% is epic.
RobI says
Good post Harry. I probably need to read it a few times to take in all the features.
I am curious how you plan to split the usage between US Bank or Fidelity for your everyday short term ‘banking’ needs. I’ve been converting to Fidelity for most transactions in last 12 months.
Harry Sit says
I listed how I will use the US Bank accounts at the end. Everything else will still use Fidelity.
Lori says
With my US Bank Cash+ card there is the option to redeem the rewards for statement credit within 3 business days vs bank deposit within 7. Is this the same with Smartly Visa? If so, is there a particular reason for going with savings deposit instead of statement credit (#3-4)? Thanks.
Harry Sit says
Redeeming for a statement credit only gives you 0.75 cent per reward point. My redemption to the savings account arrived in seconds even though it said it could take 7 days.
Lori says
Ah, that’s disappointing. There’s no difference in value from statement credit and cash back with the Cash+ card.
Mike says
I successfully opened the 4% smartly credit card and the savings account and the Smartly $450 bonus cash checking account.
I did it entirely on the phone. He told me I had to open the brokerage account on the website when I got access to it. Apparently I have to wait for the pin number to do that. The representative was adamant that I had to do the two direct deposits , not bank transfers, into my new checking account.
You mentioned that two deposits was not necessary. Can you clarify this for me?
Harry Sit says
The two or more direct deposits must be initiated from the outside. Initiating a transfer from U.S. Bank doesn’t count. You add the U.S. Bank checking account’s routing number and account number to your outside bank and request the transfer at your outside bank. U.S. Bank displays a checklist for the bonus progress. You do one for $100 as a test. When you see it counted in the progress checklist, you can do more to meet the requirements.
Lori says
The disclosure specifically mentions: “A direct deposit is an electronic deposit of your paycheck made through the Automated Clearing House (ACH) network or an electronic deposit of your government benefits, such as Social Security, from your employer or the government. Other electronic deposits or person-to-person payments are not considered a direct deposit. “
Harry Sit says
Go by what they do, not by what they say.
Lori says
Got it. Nice that they have a bonus checklist progress feature.
Eric S says
I used ACH push transfer from my Bank of America checking account to the US Bank account and it counted as a direct deposit, so I got the reward money for $8k in direct deposits. Apparently with ACH push they cannot tell if it is from an employer or govt entity.
Lori says
Ah I see. That’s good to know.
Mike says
Anyone have difficulty setting up a transfer from Fidelity Investments?
It said it couldn’t verify my account after entering the routing number and account number and it recommended using Xfinity by MasterCard to link the account but I can’t do that, yet, because I don’t have my Pin and haven’t been allowed to create a username and password, yet.
I’m unclear about doing the transfer from Fidelity. Is one of the procedures a eft and the other a ach when you link the account beforehand? I Assume it’s the link the account first type that I want?
Harry I think your article said you didn’t have to do the ach transfer because you opened the brokerage account…. perhaps I read that wrong.
Harry Sit says
The account is new. The EWS service that Fidelity uses doesn’t know it. That’s why it wants you to use Finicity. Just wait until you set up an online login with US Bank and try again. You have 90 days to complete the direct deposits for the bonus. That’s plenty of time. Just wait for everything to run its course.
I think you can register for an online login with US Bank without the debit card PIN. Have you tried it with only the checking account number?
Mike says
Yes I have tried it every way possible. Website, App and on the phone. The person on the phone was sure after going through a process of registering my telephone number and email address that I would be able to use the App to create a username and password.
Interestingly they were able to Cobrowse on my App, never seen that on an App before, but we still got asked for the pin. HOWEVER she thinks that after the telephone number is registered for 3 days that the pin request on the App will be replaced by sending me telephone text or email with a confirmation number.
I recommend that after getting your account numbers that you immediately get them to register your telephone number and email which is a process of sending you numbers to each while on the phone with them.
I’m trying to rush this process because I leave on a trip Monday and won’t have Internet and I was hoping to get everything working before I left. I’ll just finish it when I get back.
Harry BTW Gigsky offers some free Cellular at Sea Data to us Bank Altitude customs. wish I had applied for that card before they ended new customers.
Thanks for Everything Harry. Because of you I have everything setup happily at Fidelity Investments for my main transaction account and now I’ll have a 4% card at US Bank. Like you I won’t need to stay with BofA just because of the 2.62% credit card.
I’m wondering if transferring brokerage assets to someone else would get me a good bonus offer? Maybe a new article?
Sharon Jones says
Is the process similar if setting the US Bank investment account up as an IRA? Or does it have to be a Brokerage account?
Harry Sit says
Same process for an IRA.
Eric Gold says
Harry,
Thanks for the in-depth review. It convinced me to take the leap for the cash back on tax payments.
This business of ‘port-out PIN’ was news to me. So far as I tell, it is enabled automatically by Google-Fi and is supposed to be an industry standard so I am surprised that you had to ‘opt-in’.
N says
I was able to call US Bank after I had opened the checking account and get the bonus-with-2-direct-deposits promotion applied to the account even though I didn’t sign up with the promotion link. (1-800-444-1244 for the right department, tell them code 2025janchk)
S&Pat says
When we opened the checking acct in a branch, the bank staff offered us a debit card, but we declined, coz we thought “we’ll never use it anyway.” Did we make a mistake? Should we get it anyway? Thanks
Harry Sit says
When you call customer service on the brokerage side, the phone system asks for a PIN. That PIN is the debit card PIN. You don’t need a debit card if you don’t need to call customer service or you can set a PIN in a different way.
S&Pat says
On Fido site, there’s no ACH choice to transfer out from CMA acct to US Bank checking. There’s only EFT choice for transfering out. So we chose EFT. Is that ok? Thanks.
Harry Sit says
EFT is the generic term — Electronic Funds Transfer. ACH — Automated Clearing House — is the underlying mechanism that Fidelity and nearly every other bank use to transfer funds electronically. They are synonymous for our purpose.
Pat says
I push-xfered an ACH from Fido to USBank checking 1x. The $ is now visible on USBank balance. But USBank “My Progress Tracker” checklist line of “Min of 2 direct deps in 90 days” status shows “Not yet in progress”, instead of “In Progress”. What?
Since I have deposited 1 out of 2, that checklist line should show “in progress”, right?
Also, the Progress Tracker says “Your Current total direct deposit is $0”, & the status is “Not yet in progress”, although the checking bal shows the deposit from Fido.
Also, the status of “All acct owners must qualify to get this offer” is “In Progress”.
This is after I’ve “Done” all their “To Do List”, followed by “You’re all caught up!” remarks from the webpage afterwards. I wonder what else do we need to do for this check list to show “completed”.
Does anyone have this problem? Thanks so much.
Harry Sit says
The progress tracker lags by a day or two. It’ll update shortly. Nothing else to do. Just the passage of time will get everything checked on that list.
Trey says
Can anyone confirm that we don’t have to leave the $8,000 in the Smartly Checking account while waiting on the $450 bonus? We just do two push ACH deposits totaling $8,000 within 90 days and then maintain a positive balance (but it could be as low as $10 while we are waiting for the $450), right?
Harry Sit says
That’s right. I moved the money to the brokerage account to buy GABXX. I will sell GABXX and use the money to pay toward the credit card before the due date.
Mike says
I’ve been trying for 12 days to get all this setup. Their onboarding process is uncharacteristically confusing and slow. I’m now waiting for the Brokerage to be established. I called and offered any additional information they may need but they’re waiting for the back office.
How long did it take you to complete the entire process?
Harry Sit says
It took about a month to finish everything due to the small bumps mentioned in the post.
Mike says
thanks I was starting to think it was me.
Mike A says
Harry in your August 2024 post you stated:
“””I turn on 2-factor authentication in all accounts
1. If the account supports security hardware (Yubikey or Symantec VIP token), I use security hardware.
2. If the account supports authenticator apps (Google Authenticator, Microsoft Authenticator, Authy, …), I use an authenticator app.
3. If an account only supports sending security codes by text message, I give my Google Voice number and receive the code in the Google Voice app.
4. If an account doesn’t accept a Google Voice number, I close my account.
“””
https://thefinancebuff.com/google-voice-number-permanent-2fa.html
Given your strong stance on prioritizing account security, I’m curious about your reasoning behind opening four new accounts and moving $100K to a bank that does not even support Google Voice. Why the shift in your approach to financial account security?
Harry Sit says
Three of the four accounts don’t hold much money. I made an exception when the value is compelling and I’m satisfied by the security protocol at the obscure mobile carrier I use. The port-out process requires a secure chat only accessible from the mobile carrier’s website, which has 2FA. Pre-registered security answers must be given. The port-out account number and PIN are only sent to the email address on file, which is protected by hardware 2FA.
Eric Gold says
When bank 2FA is by SMS, the security is only as good as your carrier’s port-out security
Bill says
Is it recommended to wait a few days between the two push ACH deposits?
Harry Sit says
You have 90 days to complete the two push ACH deposits. Take your time. Waiting a week between deposits gives you a chance to see how the first deposit is reflected in the progress tracking checklist.
Dan says
Hello,
Does US bank brokerage accept Fidelity total US market share FSKAX? I want to transfer $100Kish in kind. If not available at US Bank, what would be the best way to transfer without incurring or at least minimize taxes? Thanks.
Might Investor says
I just moved over FSKAX. $120K just to be safe. Just be aware that — per their brokerage reps — they charge fees (approx $50) to buy or sell. I believe they told me dividend reinvestment was free, but you might want to check that with them.
Hutch Loan says
One thing I like about the Fido Visa is that the 2% just magically deposits into my specified Fidelity account and there’s nothing more for me to do. It’s not clear to me what happens to the 4% rewards on this card.
> Redeem rewards into the savings account (monthly).
Does this happen automatically or is this something you have to login to do?
> Transfer the rewards deposit from the savings account to the credit card as a payment.
Again, does this happen automatically or is this also a manual step?
Harry Sit says
Both are manual steps. You can do it in online banking or the mobile app in the same session.
Dan says
How do I know (where to look on website) that I’m qualified for 4%? I’ve done and completed everything including brokerage transfer and credit? But not sure if I should start using the card yet?
Harry Sit says
Go into your credit card account. Click on the “Go to rewards & benefits” box right above the list of card transactions. You’ll see a 2% base tier plus whatever bonus tier you’ve qualified.
Dan says
Hello, so while my account says that I earn 2%+2% bonus, my 1st purchase which recently cleared showed under reward activity: pending rewards and then listed my only purchase as 5000 points with earn rate 2%. When will it show that I will earn the +2% bonus part like in your Screenshot? I called in and asked and they said it won’t show the 2% bonus until my statement has generated? Hmmm…What do you think? Thanks.
Dan says
To clarify, I should be getting 10K points since my profile clearly stated that I should be earning 2%+2% but it doesn’t show that under my pending reward like in your screenshot? Does it take a while? Thanks.
Harry Sit says
Did you see 2% + 2% before you made that purchase? I see the 4% earn rate as soon as I see the pending reward. It sounds like you made that first purchase too soon. Try another small purchase and see if you get 4% now.
Dan says
I think you’re probably right. So on Thursday, my brokerage transfer got credited (left Fidelity on Monday). I called on Thursday and inquired whether I was eligible for 4% yet. They said yes as of Monday it showed on their end, I was already qualified? On Thursday, on website it hasn’t showed my 2+2% yet. Anyway, I went ahead and made the purchase on Thursday since they told me my account does have 4%. The purchase was cleared on Thursday and when I also happened to notice that website now indicated I have 2+2. However, my purchase only got 2% under “pending rewards” tab. So yeah that’s the timeline. Ig you’re right … maybe I should’ve waited until website shows the 2+2 before initiating any purchase. By the way, is there a way to kind of tell if they will increase my Credit Limit bc I don’t want to waste another hard pull. They’re only giving me $20K CL and $15K for my significant other …. but I need more ….actually, I wouldn’t mind applying for an additional card for ease of management either, but not sure they will approve me for another card or how long I should wait before applying….Thank you for all the help.
Harry Sit says
No good way to predict whether they’ll grant a credit limit increase. From what I read, most people got an increase when they asked for one. Some people were denied and told to request again after making six payments.
Dan says
Sorry I meant to say the purchase was cleared on Saturday and that was when I also noticed 2+2% bonus on website. I didn’t check on Friday since I figured it would take at least 2 days for purchase to go from pending to processed.
SSA says
I got my credit card and the Savings Account.
The checking account application got rejected repeatedly. Customer service wouldn’t tell me the reason why – just that the reason will be conveyed by snail mail.
Anyone experienced this or know what might cause the checking account to not be approved?
Harry Sit says
The rejections are usually due to ID verification. You can call the number in the letter you’ll receive or you can go to a branch and open the account there.
SSA says
I finally got all the accounts created. I had to call the authentication dept. to get the checking account created. I think it was caused because my primary number is my google voice number.
When I applied for the credit card and saving acct. they accepted the google voice number.
Strangely, when I log in now, as the second factor, I get a choice of my google voice number, my cell phone number & my email. I am able to login with the google voice number – so am debating whether I should risk removing the cell phone number from my account. My fear is that as soon as I remove the cell number, I will hit some US bank requirement which will need me to add the cell number back.
Z says
Thanks for the guide. Took about 4 weeks to get everything up and running.
1. Biggest delay was getting the CC in my hands. 10 business days for approval + 4 days to ship to me. $20k card limit and they only increased it by $5k when I applied online for a limit increase.
2. I signed up for the $450 checking offer online. I got an error message and had to call in. Thanks N for the tip (1-800-444-1244 for the right department, tell them code 2025janchk). Took about 5 business days for the “track your reward progress” to show up in the app and on the website. There is a 1-2 day delay for the reward tracker to be updated when your DD. Push money from the external account to get credit.
3. Took a week for some of my brokerage assets to be transferred from VG to US Bank. Cost basis was updated 3-4 days later after the assets arrived.
4. Savings account has a competitive rate with no transaction limits. It’s allowed me to reduce the amount I hold in a different checking account and use the savings account as my autopay hub.
TCW says
According to Doctor of Credit, citing Reddit posts, the Smartly card is not available to new customers and the terms and benefits are going to be revised.
Eric Gold says
lol. Rumor-mongering at its best
IN-BRANCH applications are on hold temporarily.
The product summary was updated
Ara says
so based on this, do we HAVE to have the brokerage account?
I thought having 100k in the savings account was adequate to meet the requirement.
someone said it’s very hard to pull money out, if we want to get out, such as having to go to a branch etc. any ruth to this?
Harry Sit says
No, you don’t HAVE to have the brokerage account. Having $100k in the savings account will meet the requirements but your $100k earns a lower interest rate than it could earn elsewhere. $100k worth of stocks in the brokerage account goes up and down the same as it does elsewhere.
Jackie B says
Thank you so much, Harry, for giving step-by-step tutoring on this situation. I followed your instructions and after about a month, just as you wrote, everything is moving along. I wouldn’t have done this without your detailed instructions. Thanks again; I enjoy learning from your blog.
TJ says
Well that didn’t last long – congrats to those who got in before the April 14th changes!
Lori says
I’ve noticed that the listing of rewards per transaction seems more for show than being a factual record. The rewards earned is on total statement purchases so being in the 2.5 tier, in my latest statement of $28.60 in purchases I earned 57 points at 2 points + 14 points at .5 points for a total of 71 points earned. However if you summed up the points per transaction as they’re shown in the rewards transactions online it would total 72 (38+13+4+17) points due to rounding that occurs per transaction, but isn’t what your total is based on.
The feature seemed nice at first, but I wish it wasn’t so inaccurate.
Eric says
You must be kidding.
Any single transaction will be rounded; the sum of the rounding will tend to zero as the number of transactions increases. The total points from the sum of each points per transaction is likely to differ from transaction_total * 2.5 pts/$ by a point, meaning one cent difference. Watch enough months, and I bet you can eventually see a **two** penny discrepancy.
Lori says
I’m not frustrated over the perceived loss of a penny a month, but if you’re going to have a rewards activities page with a balance and list of earned rewards by transactions that went towards said balance, the sum should equal, otherwise display the data differently.
TJ says
Harry, will you go back to Bank of America if the changed they made get expanded to all card?
Harry Sit says
If nothing better is available, sure, I would go back to B of A. I’m familiar with the setup. They’ll pay me bonuses. Everything works well there.
Wayne S says
As of September 15, 2025 the following changes take place, regardless of whether you are grandfathered in for using an investment account to reach the bonus points tiers.
1) There is a $10,000 cap on purchases that get the bonus points (anything above 2%)
2) Certain transactions are excluded from bonus points (Education, gift cards, insurance, or taxes, or third party bill payments)
I expect further downgrades in the future. It was good while it lasted.
Harry Sit says
The $10,000 cap is reset per monthly statement cycle, which isn’t too bad. I have yet to charge more than that in any month. I’ll continue to use it and observe which charges are excluded from the additional 2% if I get the good/benign letter that still counts investment accounts. Even with the reward being lowered from 4% to 2% on some charges, the blended rate should still be higher than the 2.625% from the B of A card I used to use. It all depends on which version of the letter I’ll receive.
Harry Sit says
My wife and I received two good letters today. It will be business as usual for us.
To others who haven’t heard, US Bank has sent two versions of letters to customers having this card. One version, marked “TC 16815 07/25” at the bottom right, limits the $100k required for the 4% reward to only checking and safe debit accounts, which makes it not worth it and effectively downgrades the card to a 2% reward card. This is the bad letter. The other version, marked “TC 16816 07/25” at the bottom right, still counts investment accounts for the $100k. This is the good/benign letter. What makes someone get which letter is kind of random, and you can’t do anything about it anyway. So just act accordingly. Keep going if you get the good letter. Ditch it if you get the bad letter and you don’t want a plain 2% reward card with little other benefit.
Eric Gold says
Lots of people are considering the BoA PRE card at 2.65% for all purchases as an alternative to the badly nerfed 2% for all Smartly. I don’t know if the perks are different, but the PRE requires a $100k brokerage balance for that cashback level and the card has a $99 annual fee.
I think the hard-core but not affluent maximizers will find they are better off with the 2% Smartly card, and then churning their $100k for brokerage sign-up bonuses.
Harry Sit says
Bank of America PRE is its Premium Rewards Elite, with a $550 annual fee. The (non-Elite) Premium Rewards card has a $95 annual fee. Points from the Elite card are worth 25% more if they’re redeemed for travel using B of A’s travel center. The higher fee also covers some statement credit for things you may or may not use (baggage fees, rideshare, food delivery, video streaming service, and fitness). The non-Elite card is better for me if I were to go back to B of A because I don’t want to use the travel center.
Eric says
Pure bait and switch. I will never do business with USBank again. What a terrible way to treat customers.
Eric Gold says
Comments like these make me laugh. As if US Bank is sad to lose an unprofitable account.
Eric says
Companies that treat customers like this eventually get what they deserve. A bad reputation has consequences.
Eric Gold says
US Bank is losing you, an unprofitable customer. Do you *really* think I care ? That a profitable to US Bank customer cares ? That US Bank cares ? That a stockholder cares ?
Yes to the last two. They are delighted.
What you call “terrible customer treatment” is just smart business. The only bad move US Bank made was attracting you in the first place. Same goes for me, by the way, so don’t think I am singling you out. I’m just pointing out to you that your hubris is silly. Grow up. When US Bank dumps me (and they should) I will not be offended. I enjoyed the free money while it lasted.
The way to think about these things rationally is to imagine yourself a US Bank stockholder. Would you want the bank to have you as a customer ? Would you want the bank to continue having you as a customer ? Would you want the bank to have hundreds of thousands of other customers like you ?
Eric says
I never said anything about them caring. Bait and switch is not a good business model. It MIGHT give them a bad reputation and MIGHT result in lower growth, lower profits, layoffs, etc. Just because they don’t care doesn’t mean they shouldn’t care. Your definition of smart business is obviously different than mine.
Eric Gold says
You misunderstand. US Bank DOES care. They want profitable customers.
What you inaccurately call “Bait & Switch”, every stockholder calls “getting rid of dead weight.”
I’m not a US Bank stockholder, but it is obvious that nerfing you is a good thing for the Bank’s bottom line. If/when they nerf me, the same thing will be true, if not more so.
And should they nerf me, it will not affect my decision whether to be a customer in the future in the slightest. And if in the future US Bank offers you a deal better than anywhere else, you would be a fool to say no. But be my guest, and say no. US Bank thanks you.