U.S. Bank offered a Smartly Visa card with great rewards in late 2024. They soon regretted it and pulled back the offer in April 2025. Some of us got in early and were grandfathered into the original terms with only minor modifications. If you didn’t get in early, it’s still a good card, but it’s not necessarily the best.
This isn’t a sponsored post. It contains no affiliate links. I have no relationship with any bank or broker except as a customer.
4% Rewards
The grandfathered customers receive 4% cash-back rewards on everything when they also hold $100,000 in investments in a U.S. Bankcorp Advisors account. The 4% cash-back is capped on $10,000 in net charges per statement cycle, except for taxes, education, gift cards, insurance, and business-to-business transactions.
I like this card because it’s simple after a one-time setup. I get good rewards on every purchase, and there’s no annual fee or special categories to remember and juggle. The $10,000 cap per statement cycle is high enough that I’ve never run into it. Charges in the exception categories don’t count toward the $10,000 cap, and they still earn 2% rewards.
New customers earn 4% rewards only if they hold $100,000 in a U.S. Bank checking or safe debit account, which makes it not worth it. It’s still a plain 2% rewards card with no other requirements.
Other 2% Cash-Back Cards
If you didn’t get in early and you prefer to use one card for everything, only a handful of cards from other banks offer straight 2% cash-back rewards with no special categories.
Fidelity Rewards Visa is run by a division of U.S. Bank. It has better ancillary benefits than the U.S. Bank Smartly card, but it requires a Fidelity account for the 2% cash back.
Citi Double Cash card is a Mastercard. So is Synchrony Premier World card. These 2% rewards cards aren’t accepted at Costco.
Wells Fargo Active Cash card is similar to the U.S. Bank Smartly card.
What Works Well
The 4% credit card rewards are straightforward after a one-time setup. I qualified for the maximum 4% rewards only a few days after a brokerage account transfer brought the combined balances above $100,000. For instance, this $15 transaction earned 4% in reward points:
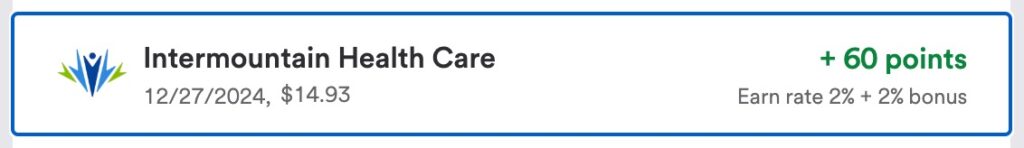
One reward point is worth $0.01 when you redeem it into a U.S. Bank checking or savings account (minimum 2,500 points = $25 per redemption). You can make a payment to the credit card from the checking or savings account.
Nice Card Design
The Smartly Visa card looks and feels premium in the hand because it’s black and metal. It doesn’t matter much though when you use Apple Pay or Google Pay.
Website and Mobile App
The U.S. Bank online banking website and mobile app work well. It was easy to set up paperless statements for all accounts and autopay for the credit card, change the PIN on the cards, and lock the debit cards.
The website supports logging in with a passkey. The mobile app supports biometric login with Face ID or fingerprint.
Transactions display nicely in online banking and the mobile app. You can download the credit card transactions in CSV or QFX format to import into personal finance software such as Quicken.
Bank of America shows this for a purchase at a Walmart:

U.S. Bank shows this:
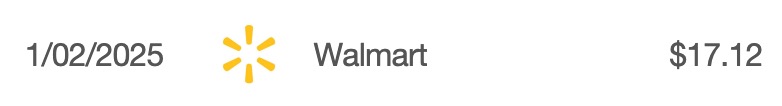
U.S. Bank translated the description “WM SUPERCENTER #4696” into a more recognizable merchant name “Walmart” with a logo. This adds a nice touch. I haven’t seen other banks doing it.
Brokerage Account
U.S. Bank’s brokerage service doesn’t advertise itself independently. Every brokerage customer is assumed to be a bank customer. You log in to the bank’s website to access the brokerage account. You use the same mobile app for both.
The brokerage account is handled by Fidelity behind the scenes. I’m holding one ETF worth a little over $100,000, which pays about $500 in dividends per quarter. I transfer the dividends to the savings account and make a payment to the credit card.
New customers don’t need the brokerage account to earn 2% rewards.
The Downsides
This setup with U.S. Bank has some downsides that don’t bother me.
Foreign Transaction Fee
The Smartly Visa card has a 3% foreign transaction fee. You still net 1% after the fee. You can use a different card for foreign transactions, but the no-fee card has to pay more than 1% on those purchases to make a difference. If you spend $5,000/year on foreign transactions, using a 2% card with no foreign transaction fee only nets you $50.
I’m inclined to just eat the 3% fee and not bother switching because I don’t spend that much on foreign transactions.
Skimpy Card Benefits
Although the card looks and feels premium physically, it comes with few ancillary benefits. It doesn’t have extended warranty or secondary rental car insurance. My old Bank of America card had those benefits, but I hadn’t had any chance to use them over 10+ years. If extended warranty or secondary rental car insurance is important to you, you must remember to use a different card on transactions you want to cover.
No FICO Score
Bank of America shows a FICO 8 credit score from TransUnion monthly at no charge if you opt in. U.S. Bank also offers a free credit score weekly, but it’s based on the VantageScore 3.0 model, which fewer lenders use. Seeing a FICO score is nice but not essential to me.
Only Email or SMS for 2FA
U.S. Bank’s website uses a passkey as an alternative to your password. The two-factor authentication only uses email or SMS. It doesn’t accept a Google Voice number for SMS. You must make sure to secure your email and mobile number. I activated the extra security feature offered by my mobile carrier to protect against unauthorized porting-out requests.
Low ACH Limits
The maximum amount of ACH push I can initiate at U.S. Bank is $1,500 per day and $3,000 per week. The low limits don’t affect me because I don’t need to transfer any money out. I’ll use the monthly credit card rewards and the quarterly dividends to pay toward the credit card.
Designating Beneficiaries Requires a Form
Designating beneficiaries for the brokerage account requires mailing a paper form or calling customer service to arrange for e-signing. It doesn’t bother me because it’s only a one-time task.
***
I’m on autopilot earning 4% rewards now. My activities in all U.S. Bank accounts come down to:
- Use the credit card for all purchases.
- U.S. Bank debits an external account on autopay (monthly).
- Redeem rewards into the savings account (monthly).
- Transfer the rewards deposit from the savings account to the credit card as a payment.
- Receive dividends in the brokerage account (quarterly).
- Transfer the dividends from the brokerage account to the savings account and make a payment to the credit card.
- Deposit paper checks to the checking account (rare).
- Transfer from the checking account to the credit card as a payment.
All money generated in the accounts stays within U.S. Bank. There won’t be any transfers to or from an external account except for autopay.
If you didn’t get in before April 2025, this card is still a plain 2% rewards card with no annual fee, no special categories, and no caps. Not many cards from other banks offer 2% rewards on everything. You’d have to juggle multiple cards for rewards higher than 2%.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.
Eric says
And one more thing. I AM a USBank preferred stock shareholder, so I do not have to imagine being a shareholder. So when you ask if I as a shareholder would want hundreds of thousands of customers like me which are unprofitable ? The answer is no. But the root of the problem is the bank using bait and switch tactics to lure customers the bank knows will be unprofitable, then to change the rules knowing some will stay. Short term profit at the expense of your reputation.
Eric Gold says
Oh ? How many shares do you own ?
US Bank made a mistake taking you on as a customer. As a shareholder, would you have them continue their mistake and continue to lose money, or admit to the mistake and correct it by dumping you ?
Eric says
You are correct. They care about short term profits over their long-term best interest (their reputation).
Eric Gold says
Their reputation is fine. They dump bad customers
Eric says
Their mistake was making promises they knew up front they could not keep.
Eric says
So a bad customer is one who follows the rules THEY set up, only to be victimized by obvious bait and switch tactics ? Do you even know what bait and switch means ?
Eric Gold says
Playing the victim card is only going to appeal to other losers. If all the losers actually never become customers again, US Bank will be overjoyed. The US Bank long-term stockholders will be overjoyed.
You signed a contract that gave you the right to leave anytime you wanted, and it gave US Bank the right to dump you anytime they wanted to. US Bank honored the contract to the letter, and when they decided you were a lousy customer, they pinned your wings.
I have no problem with US Bank. And by the way, even if you were a highly profitable customer (hah!), It is obvious that they kept to the contract terms. I *do* know what ‘bait & switch’ means, and you are not it. Not by a mile.
Eric Gold says
Nonsense. US Bank fulfilled the contract signed with you to the letter. The *entire* contract, not just the 3 sentences you find convenient to remember
Eric says
I never said what they did was illegal.
Eric Gold says
I didn’t say you did (say it was illegal)
I said your characterization of dumping you as a ‘bait & switch’ is BS
I said that your impression that dumping you will negatively effect US Bank’s reputation is silly. If anything, it *improves* US Bank’s reputation.
Harry Sit says
Let’s not worry about whether something is good or bad for the bank. They don’t listen to our assessment anyway. We only decide our own reactions, stay or leave.
If the current v1 terms had been offered in the beginning, with a per cycle cap and category exclusions, I think I still would have applied. As long as it doesn’t deteriorate further, I’m happy I got in before the offer ended.
Eric Gold says
Spot on, Harry
Eric says
As a shareholder I am concerned about what is good or bad for the bank, but you are correct, all we can do is stay or leave.
Dan says
Joint account owners with very similar spending types. User 1 with higher $20k credit limit got bad nerf letter and User 2 with $15k credit limit for good nerf letter. LOL I don’t even know what to say?!
Eric says
Does not surprise me with this company.
Jacob says
My card was approved before April 14th, but I received the bad letter.
Jackie says
Ditto 😕
Lori says
FYI US Bancorp now shows a $25 fee on the order page for purchasing GABXX. Like with VUSXX, the fee doesn’t appear to be charged, but it does mean you need to adjust your purchase amount to account for it.
Pat says
Printed this article a year ago and put off acting. Wanted ev/th joint w/ my husband, but that required he do some things on his end and we were both very preoccupied with a major health issue. Long story short: 2026, a new year – time to take care of this. Well………..no longer offered. Only way to get 4% cash back is to keep at least $100,000 in checking acct. were it would be earning next to nothing. Was told those who applied under the earlier conditions were grandfathered in. Sure wish I’d acted sooner!
Stubbie says
I just reread this whole article and given what has transpired since the initial offering of this card, I still don’t understand why Harry was so enthusiastic about jumping through all of these hoops. One hassle after another in opening up all of the accounts and then dealing with the less than stellar brokerage just to keep the required $100,000 minimum. Also, “potential” $50 annual fees. Why not just stay in the BofA/Merrill ecosystem and receive the now downgraded 4.5% on CCR cards and 2.25% (3% on travel/dining) on the Premium Rewards card? Definitely not worth all of the hassle to me but everyone is different.
I do have the US Bank Connect card mainly for the airport lounge access and 4% on gas/EV purchases. Has 4% on travel too but have found their travel categories to be much more restrictive than BofA. Will keep the Connect card since it has no annual fee but only charge travel expenses in foreign countries that I know have been covered in the past. Will use a BofA CCR card (4.5%) set for travel for all domestic travel or Premium card at new 3% for foreign.
Bottom line: an awful lot of hassle with a less than top tier company to earn an additional fraction of 1% on a portion of my yearly spend.
Lori says
I believe it was the simplicity of a 4% vs 2.625% on everything card.
Harry Sit says
Exactly! You also need $100k in a not-any-better brokerage to get 4.5% on some things (with a low per-quarter limit or by using multiple cards), 3% on some other things, and 2.25% on everything else. For us who went through a one-time setup and got grandfathered, we’re getting 4% on everything. The $10,000/month limit is high enough that I never run into it. The exceptions on taxes, education, and insurance are reasonable to me. The brokerage got better. Now it’s handled by Fidelity behind the scenes. The annual fee is gone. I’m closing my Bank of America and Merrill Edge accounts.
Eric says
I am grandfathered into the Smartly ‘good nerf’, and I think it is a wonderful card at its current rules.
FWIW, when I first read about the card I thought it was too good to be true. I decided to go through the hoops to get the card anyway since I figured it would be good for at least a year. That it has lasted longer than a year is just icing on the cake for me, albeit slightly less icing since tax payments now get 2% instead of 4%. Like some other Bogleheads, a lot of my initial attraction to the card was the 4% rebate on taxes, but since the ‘good nerf’ change I either use an alternative 3% on taxes card or use tax payments to meet SUB offers. I’m a happy and fortunate credit card user, and can only hope that the ‘good nerf’ Smartly continues.
As for BOA ? Meh. Double meh
I’ve already decided that if my Smartly is killed, I’ll migrate to a 2% anywhere card, keep my 3% on taxes card for use when no SUB is calling , and call it a day.
———–
Incidentally, my biggest aggravation with the Smartly was paying the balance (I avoid PULL transactions from outside vendors). I recently realized that Fidelity has Elan in its list of Billpay vendors, and that works like a charm.
Eric says
I was curious about your avidity to the BOA credit card system. The CCR 4.5% is ONE category, limited to $2500 of category purchases a quarter, and further limited by any grocery or wholesale purchases put on the card. If you keep a pile of cards in your wallet and are forever sorting out what card to use for what purchase, you gain $37.5 a month from that category, a net opportunity gain of no more than $20.83 a month compared to a 2% card.
If hassle is your bugaboo, that is a lot of hassle for $21.83 a month, not to mention the valuable opportunity lost for a juicy Chase SUB.
Harry Sit says
I edited the post and removed the setup information no longer relevant after the doors closed. If you got in early and were grandfathered (“good nerf”), the card works great.
It’s still not a bad card for new customers. Not that many cards offer 2% rewards on everything with no annual fee, no special categories, and no caps. You can count them on one hand. We can debate which one among this handful of cards is better than another, but this card is still better than many out there when you prefer to use one card for everything.
If you got the bad nerf, where did you go?
Stubbie says
Good info, Harry. I use the Fidelity card as my default 2% card with no fees.
Thanks for all you do.