[The next update will be on November 10, 2026, when the government publishes the CPI data for October 2026.]
Seniors 65 or older can sign up for Medicare. The government refers to people who receive Medicare as “beneficiaries.” Medicare beneficiaries must pay a premium for Medicare Part B, which covers doctors’ services, and Medicare Part D, which covers prescription drugs. The premiums paid by Medicare beneficiaries cover about 25% of the program costs for Part B and Part D. The government pays the remaining 75%.
What Is IRMAA?
Medicare imposes surcharges on higher-income beneficiaries. The theory is that higher-income beneficiaries can afford to pay more for their healthcare. Instead of doing a 25:75 split with the government, they must pay a higher share of the program costs.
The surcharge is called IRMAA, which stands for Income-Related Monthly Adjustment Amount. This applies to both Traditional Medicare (Part B and Part D) and Medicare Advantage plans.
According to a Medicare Trustees Report, less than 10% of Medicare Part B beneficiaries paid IRMAA. The extra premiums they paid reduced the government’s share of the total Part B and Part D expenses by two percentage points. Big deal?
History of IRMAA
IRMAA was added to Medicare by the Medicare Prescription Drug, Improvement, and Modernization Act of 2003. The Republican Congress under President George W. Bush passed it in November 2003.
IRMAA started with only Part B. The Patient Protection and Affordable Care Act, passed in 2010 by the Democratic Congress under President Obama, expanded IRMAA to include Part D as well.
The Bipartisan Budget Act of 2018, passed by the Republican Congress under President Trump, added a new tier for people with the highest incomes.
IRMAA has been the law of the land for over 20 years. Different Congresses and administrations from different parties made small tweaks, but its structure hasn’t changed much since the beginning. IRMAA has become a bipartisan consensus. There’s no impetus for major changes.
MAGI
The income used to determine IRMAA is your Modified Adjusted Gross Income (MAGI) — which is your AGI plus tax-exempt interest and dividends from muni bonds — from two years ago. Your 2024 MAGI determines your IRMAA in 2026. Your 2025 MAGI determines your IRMAA in 2027. Your 2026 MAGI determines your IRMAA in 2028.
There are many definitions of MAGI for different purposes. The MAGI for ACA health insurance subsidies includes 100% of the Social Security benefits. The MAGI for IRMAA includes taxable Social Security benefits, but not untaxed Social Security benefits. If you read somewhere else that says untaxed Social Security benefits are included in MAGI, they’re talking about a different MAGI, not the MAGI for IRMAA.
You can use Calculator: How Much of My Social Security Benefits Is Taxable? to calculate the taxable portion of your Social Security benefits. The new 2025 Trump tax law didn’t change how Social Security is taxed. It didn’t change anything related to MAGI for IRMAA. See Social Security Is Still Taxed Under the New 2025 Trump Tax Law.
As if it’s not complicated enough, while not moving the needle much, IRMAA is divided into five income brackets. Depending on the income, higher-income beneficiaries pay 35%, 50%, 65%, 80%, or 85% of the program costs instead of 25%. As a result, they pay 1.4, 2.0, 2.6, 3.2, or 3.4 times the standard Medicare premium.
The threshold for each bracket can cause a sudden increase in the monthly premium amount you pay. If your income crosses into the next bracket by $1, your Medicare premiums can suddenly jump by over $1,000 per year. If you are married and filing a joint tax return, and both of you are on Medicare, $1 more in income can make Medicare premiums jump by over $1,000/year for each of you.
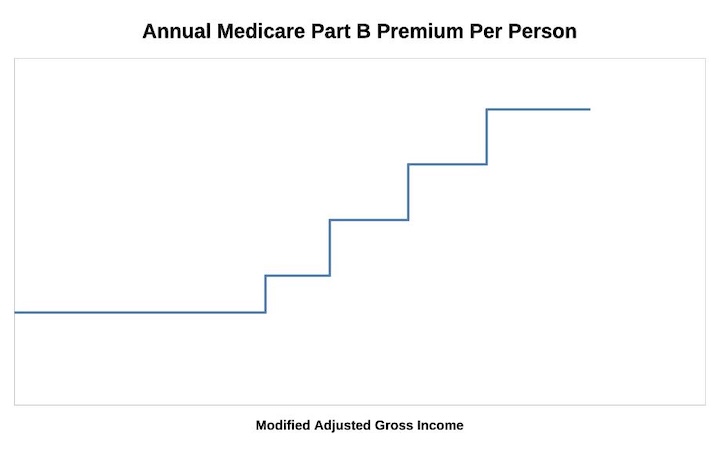
* The last bracket on the far right isn’t displayed in the chart.
If your income is near a bracket cutoff, try to keep it low and stay in a lower bracket. Using income from two years ago makes it more difficult to manage.
2026 IRMAA Brackets
The standard Part B premium in 2026 is $202.90 per person per month. The income on your 2024 federal tax return (filed in 2025) is compared against the following income brackets to determine the IRMAA you pay in 2026.
| Part B Premium | 2026 Coverage (2024 Income) |
|---|---|
| Standard | Single: <= $109,000 Married Filing Jointly: <= $218,000 Married Filing Separately <= $109,000 |
| 1.4x Standard | Single: <= $137,000 Married Filing Jointly: <= $274,000 |
| 2.0x Standard | Single: <= $171,000 Married Filing Jointly: <= $342,000 |
| 2.6x Standard | Single: <= $205,000 Married Filing Jointly: <= $410,000 |
| 3.2x Standard | Single: < $500,000 Married Filing Jointly: < $750,000 Married Filing Separately < $391,000 |
| 3.4x Standard | Single: >= $500,000 Married Filing Jointly: >= $750,000 Married Filing Separately >= $391,000 |
Source: CMS news release
Higher-income Medicare beneficiaries also pay a surcharge for Part D. The IRMAA income brackets are the same for Part B and Part D. The Part D IRMAA surcharges are relatively lower in dollars.
2027 IRMAA Brackets
We have all 11 data points needed for the 2027 IRMAA brackets (based on 2025 income), but it’s still not clear how the Social Security Administration will calculate the 12-month average with only 11 data points. The government did not and will not publish the CPI number for October 2025 because it didn’t collect the necessary price data during a government shutdown.
The Treasury Department used 325.604 as the October CPI to calculate interest on inflation-indexed Treasury bonds. The Social Security Administration won’t necessarily use the same number for IRMAA. I calculated the 2027 brackets in two ways: (a) using a straight average of the projected 11 monthly data points, omitting October 2025; and (b) using 325.604 for October 2025. The 2027 brackets are largely the same under the two methods due to rounding. I put an asterisk on the number calculated by method (b) where they differ.
The income on your 2025 federal tax return (filed in 2026) is compared against the following income brackets to determine the IRMAA you pay in 2027.
| Part B Premium | 2027 Coverage (2025 Income) |
|---|---|
| Standard | Single: <= $112,000 Married Filing Jointly: <= $224,000 Married Filing Separately <= $112,000 |
| 1.4x Standard | Single: <= $141,000* or $142,000 Married Filing Jointly: <= $282,000* or $284,000 |
| 2.0x Standard | Single: <= $176,000* or $177,000 Married Filing Jointly: <= $352,000* or $354,000 |
| 2.6x Standard | Single: <= $211,000* or $212,000 Married Filing Jointly: <= $422,000* or $424,000 |
| 3.2x Standard | Single: < $500,000 Married Filing Jointly: < $750,000 Married Filing Separately < $388,000 |
| 3.4x Standard | Single: >= $500,000 Married Filing Jointly: >= $750,000 Married Filing Separately >= $388,000 |
If you’re married filing separately, you may have noticed that the 3.2x bracket goes down from 2026. That’s not a typo. If you look up the history of that bracket (under heading C), you’ll see it went down from one year to the next. That’s the law. It puts more people married filing separately with a high income into the 3.4x bracket.
I also have the tax brackets for 2027. Please read 2027 Tax Brackets, Standard Deduction, Capital Gains, QCD if you’re interested.
The government hasn’t announced the 2027 standard Medicare Premium yet. It’s $202.90 per person per month in 2026. A previous estimate puts it at $209.50 for 2027.
2028 IRMAA Brackets
We have one data point right now out of the 12 needed for the IRMAA brackets in 2028 (based on 2026 income). We can only make preliminary estimates and plan for some margin to stay clear of the cutoff points.
If annualized inflation from October 2026 through August 2027 is 0% (prices staying flat at the latest level) or 3% (approximately a 0.25% increase every month), these will be the numbers to compare against the income on your 2026 federal tax return (to be filed in 2027) to determine the IRMAA you pay in 2028.
| Part B Premium | 2028 Coverage (2026 Income) 0% Inflation | 2028 Coverage (2026 Income) 3% Inflation |
|---|---|---|
| Standard | Single: <= $115,000 Married Filing Jointly: <= $230,000 Married Filing Separately <= $115,000 | Single: <= $116,000 Married Filing Jointly: <= $232,000 Married Filing Separately <= $116,000 |
| 1.4x Standard | Single: <= $145,000 Married Filing Jointly: <= $290,000 | Single: <= $147,000 Married Filing Jointly: <= $294,000 |
| 2.0x Standard | Single: <= $180,000 Married Filing Jointly: <= $360,000 | Single: <= $183,000 Married Filing Jointly: <= $366,000 |
| 2.6x Standard | Single: <= $216,000 Married Filing Jointly: <= $432,000 | Single: <= $219,000 Married Filing Jointly: <= $438,000 |
| 3.2x Standard | Single: < $511,000 Married Filing Jointly: < $766,500 Married Filing Separately < $396,000 | Single: < $518,000 Married Filing Jointly: < $777,000 Married Filing Separately < $402,000 |
| 3.4x Standard | Single: >= $511,000 Married Filing Jointly: >= $766,500 Married Filing Separately >= $396,000 | Single: >= $518,000 Married Filing Jointly: >= $777,000 Married Filing Separately >= $402,000 |
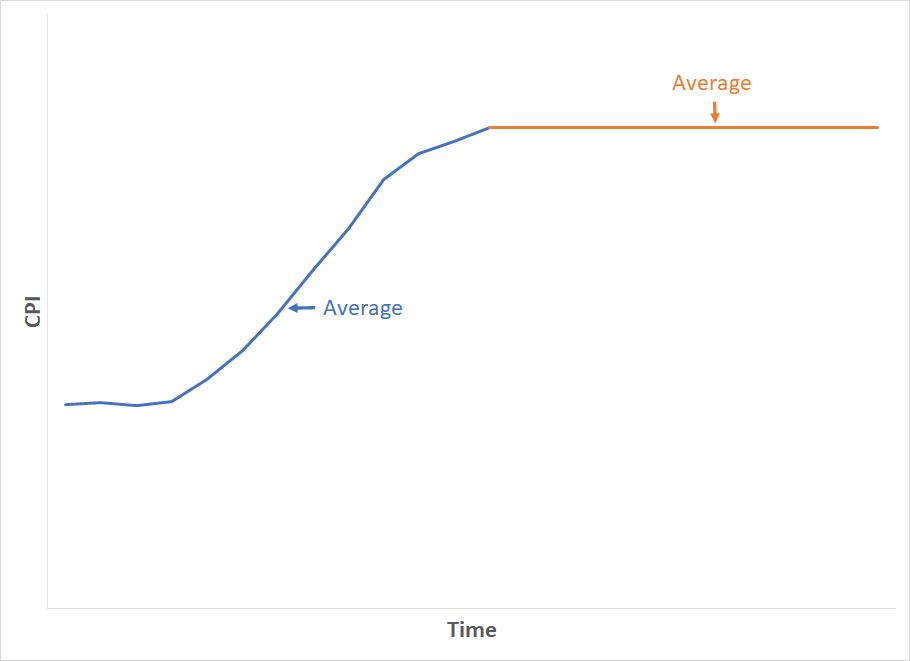
Because the formula compares the average of 12 monthly CPI numbers over the average of 12 monthly CPI numbers in a base period, even if prices stay the same in the following months, the average of the next 12 months will still be higher than the average in the previous 12 months.
To use hypothetical numbers, suppose gas prices went up from $4/gallon to $4.50/gallon over the last 12 months. The average gas price in the last 12 months was maybe $4.20/gallon. When gas price inflation becomes 0%, it means it stays at the current price of $4.50/gallon. The average for the next 12 months is $4.50/gallon. Brackets based on an average gas price of $4.50/gallon in the next 12 months will be higher than brackets based on an average gas price of $4.20/gallon in the previous 12 months.
If you really want to get into the weeds of the methodology for these calculations, please read this reply on comment page 2 and this other comment on page 4.
Effect of the Iran War
The CPI numbers in recent months were affected by volatile energy prices due to the Iran war. The 0% inflation numbers assume that prices will stay at the current level. Energy prices can drop when the war ends. If that happens, CPI numbers in the upcoming months can drop below the 0% inflation estimate, which may bring the IRMAA numbers below the projections.
Track Records
I have been doing these projections for at least six years. Someone asked me how close my past projections were to the actual numbers from the government in the following year. I went back and looked at them. The 0% inflation projections were lower than the actuals, by design. The 3% inflation projections either matched the actuals or came slightly lower. Please review the detail in How Close Were the IRMAA Income Bracket Projections?.
Roth Conversion Tools
When you manage your income by doing Roth conversions, you must watch your MAGI carefully to avoid accidentally crossing one of these IRMAA thresholds by a small amount and triggering higher Medicare premiums.
I created a Tax Calculator for Retirees to help with calculating how much to convert to Roth. It shows how much tax you’ll pay for your Roth conversion, how far you can go at that tax rate, where you will likely land in IRMAA, and how close you are to the next IRMAA threshold.
Nickel and Dime
The standard Medicare Part B premium is $202.90/month in 2026. A 40% surcharge on the Medicare Part B premium is $974/year per person or $1,948/year for a married couple both on Medicare.
In the grand scheme, when a couple on Medicare has over $218,000 in income, they’re already paying a large amount in taxes. Does making them pay another $2,000 make that much difference? It’s less than 1% of their income, but nickel-and-diming just makes people mad. People caught by surprise when their income crosses into a higher bracket by just a small amount are angry at the government. Rolling it all into the income tax would be much more effective.
Oh well, if you are on Medicare, watch your income and don’t accidentally cross a line for IRMAA.
IRMAA Appeal
If your income two years ago was higher because you were working at that time, and now your income is significantly lower because you retired (“work reduction” or “work stoppage”), you can appeal the IRMAA initial determination. The “life-changing events” that make you eligible for an appeal include:
- Death of spouse
- Marriage
- Divorce or annulment
- Work reduction
- Work stoppage
- Loss of income from income producing property
- Loss or reduction of certain kinds of pension income
You file an appeal with the Social Security Administration by filling out Form SSA-44 to show that although your income was higher two years ago, you have a reduced income now due to one of the life-changing events above. For more information on the appeal, see Medicare Part B Premium Appeals.
Not Penalized For Life
If your income two years ago was higher and you don’t have a life-changing event that makes you qualify for an appeal, you will pay the higher Medicare premiums for one year. The IRMAA surcharge goes into the Medicare budget. It helps to keep Medicare going for other seniors on Medicare.
IRMAA is re-evaluated every year as your income changes. If your higher income two years ago was due to a one-time event, such as realizing capital gains or taking a large withdrawal from your IRA, your IRMAA will decrease automatically when your income comes down in the following year. It’s not the end of the world to pay IRMAA for one year.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.
Rosanne Reynolds says
Thanks very much Jeff. Very helpful.
Best,
Rosanne