[The next update will be on November 10, 2026, when the government publishes the CPI data for October 2026.]
Seniors 65 or older can sign up for Medicare. The government refers to people who receive Medicare as “beneficiaries.” Medicare beneficiaries must pay a premium for Medicare Part B, which covers doctors’ services, and Medicare Part D, which covers prescription drugs. The premiums paid by Medicare beneficiaries cover about 25% of the program costs for Part B and Part D. The government pays the remaining 75%.
What Is IRMAA?
Medicare imposes surcharges on higher-income beneficiaries. The theory is that higher-income beneficiaries can afford to pay more for their healthcare. Instead of doing a 25:75 split with the government, they must pay a higher share of the program costs.
The surcharge is called IRMAA, which stands for Income-Related Monthly Adjustment Amount. This applies to both Traditional Medicare (Part B and Part D) and Medicare Advantage plans.
According to a Medicare Trustees Report, less than 10% of Medicare Part B beneficiaries paid IRMAA. The extra premiums they paid reduced the government’s share of the total Part B and Part D expenses by two percentage points. Big deal?
History of IRMAA
IRMAA was added to Medicare by the Medicare Prescription Drug, Improvement, and Modernization Act of 2003. The Republican Congress under President George W. Bush passed it in November 2003.
IRMAA started with only Part B. The Patient Protection and Affordable Care Act, passed in 2010 by the Democratic Congress under President Obama, expanded IRMAA to include Part D as well.
The Bipartisan Budget Act of 2018, passed by the Republican Congress under President Trump, added a new tier for people with the highest incomes.
IRMAA has been the law of the land for over 20 years. Different Congresses and administrations from different parties made small tweaks, but its structure hasn’t changed much since the beginning. IRMAA has become a bipartisan consensus. There’s no impetus for major changes.
MAGI
The income used to determine IRMAA is your Modified Adjusted Gross Income (MAGI) — which is your AGI plus tax-exempt interest and dividends from muni bonds — from two years ago. Your 2024 MAGI determines your IRMAA in 2026. Your 2025 MAGI determines your IRMAA in 2027. Your 2026 MAGI determines your IRMAA in 2028.
There are many definitions of MAGI for different purposes. The MAGI for ACA health insurance subsidies includes 100% of the Social Security benefits. The MAGI for IRMAA includes taxable Social Security benefits, but not untaxed Social Security benefits. If you read somewhere else that says untaxed Social Security benefits are included in MAGI, they’re talking about a different MAGI, not the MAGI for IRMAA.
You can use Calculator: How Much of My Social Security Benefits Is Taxable? to calculate the taxable portion of your Social Security benefits. The new 2025 Trump tax law didn’t change how Social Security is taxed. It didn’t change anything related to MAGI for IRMAA. See Social Security Is Still Taxed Under the New 2025 Trump Tax Law.
As if it’s not complicated enough, while not moving the needle much, IRMAA is divided into five income brackets. Depending on the income, higher-income beneficiaries pay 35%, 50%, 65%, 80%, or 85% of the program costs instead of 25%. As a result, they pay 1.4, 2.0, 2.6, 3.2, or 3.4 times the standard Medicare premium.
The threshold for each bracket can cause a sudden increase in the monthly premium amount you pay. If your income crosses into the next bracket by $1, your Medicare premiums can suddenly jump by over $1,000 per year. If you are married and filing a joint tax return, and both of you are on Medicare, $1 more in income can make Medicare premiums jump by over $1,000/year for each of you.
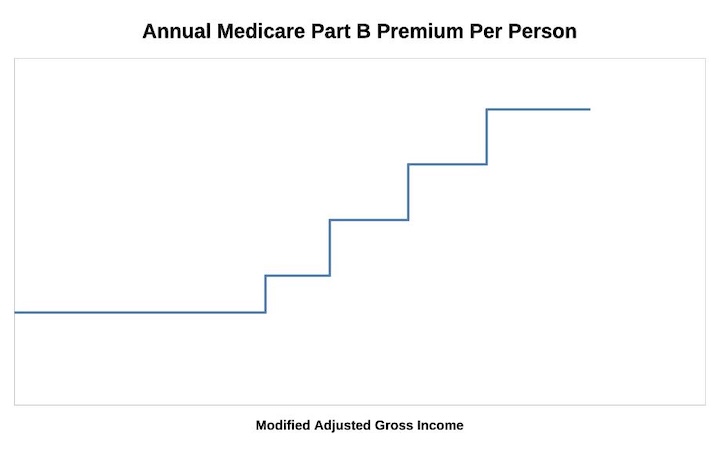
* The last bracket on the far right isn’t displayed in the chart.
If your income is near a bracket cutoff, try to keep it low and stay in a lower bracket. Using income from two years ago makes it more difficult to manage.
2026 IRMAA Brackets
The standard Part B premium in 2026 is $202.90 per person per month. The income on your 2024 federal tax return (filed in 2025) is compared against the following income brackets to determine the IRMAA you pay in 2026.
| Part B Premium | 2026 Coverage (2024 Income) |
|---|---|
| Standard | Single: <= $109,000 Married Filing Jointly: <= $218,000 Married Filing Separately <= $109,000 |
| 1.4x Standard | Single: <= $137,000 Married Filing Jointly: <= $274,000 |
| 2.0x Standard | Single: <= $171,000 Married Filing Jointly: <= $342,000 |
| 2.6x Standard | Single: <= $205,000 Married Filing Jointly: <= $410,000 |
| 3.2x Standard | Single: < $500,000 Married Filing Jointly: < $750,000 Married Filing Separately < $391,000 |
| 3.4x Standard | Single: >= $500,000 Married Filing Jointly: >= $750,000 Married Filing Separately >= $391,000 |
Source: CMS news release
Higher-income Medicare beneficiaries also pay a surcharge for Part D. The IRMAA income brackets are the same for Part B and Part D. The Part D IRMAA surcharges are relatively lower in dollars.
2027 IRMAA Brackets
We have all 11 data points needed for the 2027 IRMAA brackets (based on 2025 income), but it’s still not clear how the Social Security Administration will calculate the 12-month average with only 11 data points. The government did not and will not publish the CPI number for October 2025 because it didn’t collect the necessary price data during a government shutdown.
The Treasury Department used 325.604 as the October CPI to calculate interest on inflation-indexed Treasury bonds. The Social Security Administration won’t necessarily use the same number for IRMAA. I calculated the 2027 brackets in two ways: (a) using a straight average of the projected 11 monthly data points, omitting October 2025; and (b) using 325.604 for October 2025. The 2027 brackets are largely the same under the two methods due to rounding. I put an asterisk on the number calculated by method (b) where they differ.
The income on your 2025 federal tax return (filed in 2026) is compared against the following income brackets to determine the IRMAA you pay in 2027.
| Part B Premium | 2027 Coverage (2025 Income) |
|---|---|
| Standard | Single: <= $112,000 Married Filing Jointly: <= $224,000 Married Filing Separately <= $112,000 |
| 1.4x Standard | Single: <= $141,000* or $142,000 Married Filing Jointly: <= $282,000* or $284,000 |
| 2.0x Standard | Single: <= $176,000* or $177,000 Married Filing Jointly: <= $352,000* or $354,000 |
| 2.6x Standard | Single: <= $211,000* or $212,000 Married Filing Jointly: <= $422,000* or $424,000 |
| 3.2x Standard | Single: < $500,000 Married Filing Jointly: < $750,000 Married Filing Separately < $388,000 |
| 3.4x Standard | Single: >= $500,000 Married Filing Jointly: >= $750,000 Married Filing Separately >= $388,000 |
If you’re married filing separately, you may have noticed that the 3.2x bracket goes down from 2026. That’s not a typo. If you look up the history of that bracket (under heading C), you’ll see it went down from one year to the next. That’s the law. It puts more people married filing separately with a high income into the 3.4x bracket.
I also have the tax brackets for 2027. Please read 2027 Tax Brackets, Standard Deduction, Capital Gains, QCD if you’re interested.
The government hasn’t announced the 2027 standard Medicare Premium yet. It’s $202.90 per person per month in 2026. A previous estimate puts it at $209.50 for 2027.
2028 IRMAA Brackets
We have one data point right now out of the 12 needed for the IRMAA brackets in 2028 (based on 2026 income). We can only make preliminary estimates and plan for some margin to stay clear of the cutoff points.
If annualized inflation from October 2026 through August 2027 is 0% (prices staying flat at the latest level) or 3% (approximately a 0.25% increase every month), these will be the numbers to compare against the income on your 2026 federal tax return (to be filed in 2027) to determine the IRMAA you pay in 2028.
| Part B Premium | 2028 Coverage (2026 Income) 0% Inflation | 2028 Coverage (2026 Income) 3% Inflation |
|---|---|---|
| Standard | Single: <= $115,000 Married Filing Jointly: <= $230,000 Married Filing Separately <= $115,000 | Single: <= $116,000 Married Filing Jointly: <= $232,000 Married Filing Separately <= $116,000 |
| 1.4x Standard | Single: <= $145,000 Married Filing Jointly: <= $290,000 | Single: <= $147,000 Married Filing Jointly: <= $294,000 |
| 2.0x Standard | Single: <= $180,000 Married Filing Jointly: <= $360,000 | Single: <= $183,000 Married Filing Jointly: <= $366,000 |
| 2.6x Standard | Single: <= $216,000 Married Filing Jointly: <= $432,000 | Single: <= $219,000 Married Filing Jointly: <= $438,000 |
| 3.2x Standard | Single: < $511,000 Married Filing Jointly: < $766,500 Married Filing Separately < $396,000 | Single: < $518,000 Married Filing Jointly: < $777,000 Married Filing Separately < $402,000 |
| 3.4x Standard | Single: >= $511,000 Married Filing Jointly: >= $766,500 Married Filing Separately >= $396,000 | Single: >= $518,000 Married Filing Jointly: >= $777,000 Married Filing Separately >= $402,000 |
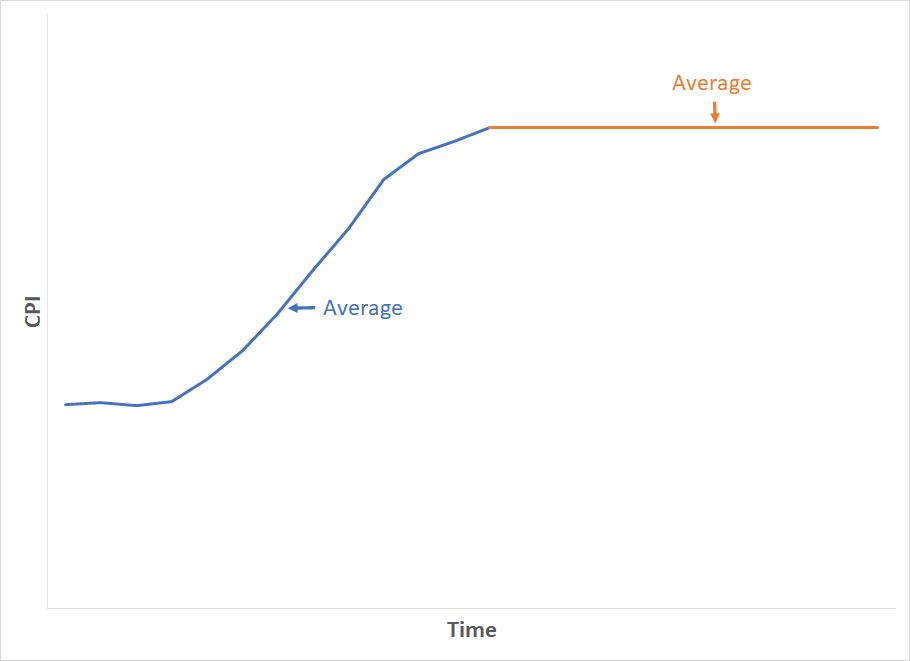
Because the formula compares the average of 12 monthly CPI numbers over the average of 12 monthly CPI numbers in a base period, even if prices stay the same in the following months, the average of the next 12 months will still be higher than the average in the previous 12 months.
To use hypothetical numbers, suppose gas prices went up from $4/gallon to $4.50/gallon over the last 12 months. The average gas price in the last 12 months was maybe $4.20/gallon. When gas price inflation becomes 0%, it means it stays at the current price of $4.50/gallon. The average for the next 12 months is $4.50/gallon. Brackets based on an average gas price of $4.50/gallon in the next 12 months will be higher than brackets based on an average gas price of $4.20/gallon in the previous 12 months.
If you really want to get into the weeds of the methodology for these calculations, please read this reply on comment page 2 and this other comment on page 4.
Effect of the Iran War
The CPI numbers in recent months were affected by volatile energy prices due to the Iran war. The 0% inflation numbers assume that prices will stay at the current level. Energy prices can drop when the war ends. If that happens, CPI numbers in the upcoming months can drop below the 0% inflation estimate, which may bring the IRMAA numbers below the projections.
Track Records
I have been doing these projections for at least six years. Someone asked me how close my past projections were to the actual numbers from the government in the following year. I went back and looked at them. The 0% inflation projections were lower than the actuals, by design. The 3% inflation projections either matched the actuals or came slightly lower. Please review the detail in How Close Were the IRMAA Income Bracket Projections?.
Roth Conversion Tools
When you manage your income by doing Roth conversions, you must watch your MAGI carefully to avoid accidentally crossing one of these IRMAA thresholds by a small amount and triggering higher Medicare premiums.
I created a Tax Calculator for Retirees to help with calculating how much to convert to Roth. It shows how much tax you’ll pay for your Roth conversion, how far you can go at that tax rate, where you will likely land in IRMAA, and how close you are to the next IRMAA threshold.
Nickel and Dime
The standard Medicare Part B premium is $202.90/month in 2026. A 40% surcharge on the Medicare Part B premium is $974/year per person or $1,948/year for a married couple both on Medicare.
In the grand scheme, when a couple on Medicare has over $218,000 in income, they’re already paying a large amount in taxes. Does making them pay another $2,000 make that much difference? It’s less than 1% of their income, but nickel-and-diming just makes people mad. People caught by surprise when their income crosses into a higher bracket by just a small amount are angry at the government. Rolling it all into the income tax would be much more effective.
Oh well, if you are on Medicare, watch your income and don’t accidentally cross a line for IRMAA.
IRMAA Appeal
If your income two years ago was higher because you were working at that time, and now your income is significantly lower because you retired (“work reduction” or “work stoppage”), you can appeal the IRMAA initial determination. The “life-changing events” that make you eligible for an appeal include:
- Death of spouse
- Marriage
- Divorce or annulment
- Work reduction
- Work stoppage
- Loss of income from income producing property
- Loss or reduction of certain kinds of pension income
You file an appeal with the Social Security Administration by filling out Form SSA-44 to show that although your income was higher two years ago, you have a reduced income now due to one of the life-changing events above. For more information on the appeal, see Medicare Part B Premium Appeals.
Not Penalized For Life
If your income two years ago was higher and you don’t have a life-changing event that makes you qualify for an appeal, you will pay the higher Medicare premiums for one year. The IRMAA surcharge goes into the Medicare budget. It helps to keep Medicare going for other seniors on Medicare.
IRMAA is re-evaluated every year as your income changes. If your higher income two years ago was due to a one-time event, such as realizing capital gains or taking a large withdrawal from your IRA, your IRMAA will decrease automatically when your income comes down in the following year. It’s not the end of the world to pay IRMAA for one year.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.
Rosanne Reynolds says
Thanks very much Jeff. Very helpful.
Best,
Rosanne
Darrell Woods says
Thank You for this information. I visit your site at least once a month to see your latest estimates, in order to plan/minimize my IRMAA costs! It is a GREAT planning tool. Again, THANKS
Russ says
Great model! Best part is it confirms my self built spreadsheet to the dollar while I feel a lot more confident with yours!
Ros says
Thank you for the update. I was just going to verify my income again for this year.
Has the number ever gone down in the following year for the year before when it was
too late to manipulate your income for premium in the next year? If not do you have an inclination that it may happen for this years income? Not asking for a definate answer just an inclination with working with this for so many years.
Ros
Harry Sit says
I included some history in How Close Were the IRMAA Income Bracket Projections?. The 0% inflation numbers as of December were always lower than the actual numbers published in the following year. The “some inflation” (currently 3%) numbers either matched or were slightly lower than the actual numbers, but they were cutting it close. Obviously there are no guarantees, but I’m comfortable with the 0% inflation numbers after the December update.
Ros says
I thank you again for your time and consideration in answering this so fast.
I am very concerned about the economy from January 2027 through August 2027 for 2026 income. I believe that is the last that the number can change for 2026 income.
So I am hoping it won’t go down lower that $114,000. Thank you
for answering so quickly. I would like to do a Roth conversion.
I hope to stay below $112,000.
Richard Regal says
If you just take a simple approach of using a projected inflation rate and continuing the series then it will not even hit $114k unless annual inflation between now and August is -0.8% (prices 0.73% lower than now) and would not hit $112,000 unless it is -4.6% with prices being 4.2% lower than now (in which case we would all have much worse problems). If you try to adjust for seasonal variation then it will hit $114,000 at -0.4% inflation (prices .3% lower than now) and $112,000 at -4.2% (prices 3.8% lower than now). (I am more than willing to share my spreadsheet.)
I think deflation/recession/depression to the 4% level is extremely unlikely so $112,000 is, IMV, safe.
Ros says
Richard, Thank you but I can’t think of a way to get your spreadsheet. I have copied and pasted you post.
I worked in a bank and was a twp treasuring during the 80’s after OPEC formed in the 70’s and oil went from 17.9¢ a gallon when we built our 2nd home and we filled a 2,000 gallon tank for heat for $400 with delivery and sales tax and oil went up to over $1.25 in the 1980’s when my husband built a wood boiler. We had 4 thermosts so we could regulate the heat in differents parts of the 2 story home plus a walk out basement. We had 60 acres and could cut the junk trees or a dying tree. . He even made a log splitter and only we only had to buy the hydrolics for $57 when the log splitters were over $1,000 back then. In the 80’s home loans went up to 18.7% for a short while, we had 13% unemployment in my state one January, 2 recessions after a tax cut, and the slogan given was “A RISING TIDE WILL LIFT ALL BOATS” to push the tax cut. Just hope I am not over reacting now. Would not want families to go through that again. It was decades before many families were made whole again.
Richard Regal says
Ros,
If you drop me a line on [redacted] I can e-mail you the 2 sheets (one for the simple and one for seasonal).
ros says
I just noticed while reading this site again that all the increments go up .6 per increase except the last bracket. As a result, they pay 1.4, 2.0, 2.6, 3.2, or 3.4 times the standard Medicare premium. Why don’t the wealthiest of retirees that do not self insure have to pay the same increase?
Richard Regal says
It is a question of how much of the cost of part be coverage the individual pays and how much the government pays. The standard rate is calculated so that the individual pays 25% of the cost and the government pays 75%
Here is a table showing the relevant percentages
Individual Medicare
Standard 25% 75%
1.4× 35% 65%
2.0× 50% 50%
2.6× 65% 35%
3.2× 80% 20%
3.4× 85% 15%
The closer you get to 4 times the standard premium the less room there is to raise the multiple (90% would be 3.6 for example).
I think a more accurate name for IRMAA would be Income Related Subsidy Reduction Amount.
Tom P says
If it’s any consulation the top two brackets are now indexed to inflation. Previously the 5th tier was capped at $750,000 and the 6th was anything over that cap. Now the 5th adjusts and th 6th follows suit. The top bracket pays 85% of the cost and the bottom bracket without IRMAA pays 25.5%.
Ros says
Thank you. Just curious.
Mike W says
Just a theoretical question. Assume I am a Gazillionaire. Can I drop all government provided healthcare forever?
Harry Sit says
Of course you can, but it’s also unnecessary. Part A is free. You still get 15% subsidy after you pay 3.4x for Part B.
David says
Do Medicare Part D increases use the same basis as those for Part B?
Tom P says
David, the Part D uses a different methond than Part B. Part B uses the factors 1.0, 1.4, 2.0, 2.6, 3.2 and 3.4 for the various IRMAA tier multipliers. Part D adjustment factors are calculated from the percentages people pay for Part B coverage. For the Part B tiers listed above these are 25.5, 35, 50, 65, 80 and 85.
The part D factors are then calculated as:
(35-25.5)/25.5, (50-25.5)/25.5, … (85-25.5)/25.5
These factors are then applied to the Part D Base Amount, which is availble about the end of July each year from https://www.cms.gov/medicare/payment/medicare-advantage-rates-statistics/ratebooks-supporting-data.
For 2026 the Part D Base is $38.99 and the adjustment amounts are $14.50, $37.50, $60.40, $83.30 and $91.00. For 2027 the Part D Base will be $41.33 per the above link.
Harry Sit says
The income brackets are the same, though. The multipliers are slightly different from the Part B multipliers now and will be a lot different starting in 2030. The amount being multiplied is a base amount identical for everyone, not related to the specific plan you select.
Jeff Enders says
this may be simpler. Medicare’s forecasted premium and charges for each IRMAA tier are on pages 209 and 212 of the annual report.
https://www.cms.gov/oact/tr/2026
Walt Driver says
Just curious…but if things were to ‘go south’ and there was negative inflation (deflation??), could the IRMAA brackets possibly go down….or would they simply not increase?
Thx
Richard Regal says
The consensus view here is that they could go down but not below the 2016 brackets. My personal view is that the government would find a way to interpret the legislation so that they merely do not increase.
For 2027 the first bracket has already been set at $114k for married filing jointly. If prices remain as they are then for 2028 it will rise to $115k. At current inflation levels (or even if the Fed hits its 2% target) it will rise to $116k.
Now for your question. If prices next August are a little bit lower than they are now then the 2028 first bracket (which will use your 2026 income to be tested against) will remain at $114k. If prices next August are about 2% lower than they are now then the bracket could fall to $113k.
However remember these figures are for the overall price level between now and then. For every month that inflation stays at the current level, the rate at which they have to fall between when that stops and next August rises steeply. With just 2 more months of 3% inflation then if prices remain at that level you are at $115k. Prices would have to fall by just over 1% between then and August to hit $114k and nearly 5% to hit $113k
Steve says
For those of us who own mutual funds in taxable accounts and want to avoid unexpected promotions into higher IRMAA brackets, this is the month to estimate end-of-year dividend and capital gain distributions from those funds. I own a Vanguard actively managed fund that has realized gains of 10% of share price as of Sep. 30. That will result in a taxable capital gain distribution in December of almost twice what it was in 2025.
Article linked below says Vanguard’s active funds are on pace for their biggest payouts in more than two decades. That is likely the case for funds run by other companies.
https://www.independentvanguardadviser.com/capital-gains-sneak-peek-2026/
I just learned that I can get a good estimate of end-of-year cap gains by looking up realized gains reported by Vanguard, even before Vanguard issues its preliminary distribution estimates.
End-of-year taxable distribution info is useful to enable tax planning to avoid accidentally moving up to a higher IRMAA bracket.
Jeff Enders says
Steve – all the more reason to own ETFs and not mututal funds 🙂
Steve says
Jeff: True. ETFs can be more tax efficient than actively managed mutual funds.
Some of us diligently dollar cost average invested in mutual funds before ETFs existed.
I wonder what lessons today’s investors will learn from hindsight in 25-30 years.
The Wizard says
In your taxable account, it’s best to own INDEX funds, whether ETFs or MFs.
while most ETFs are indeed index funds, there are a few now that are managed funds and hence the possibility of CGDs.
I own VOO, QQQ, VGT, and MGK in taxable. All are index funds, hence no CGDs…
Jeff Enders says
The wizard – Regardless of what a fund is invested in, the issue is the legal structure of the fund – either ETF or mutual fund. The 4 index funds you noted are all legally “ETFs”.
An “index fund” can be either a mutual fund or an ETF. In today’s environment, most, but not all legally structured as ETFs.
The price of an ETF will fluctuate during the trading day to reflect the underlying value of its investements. A Mutual fund will re-set its price daily at 4 p.m. (ET) based on the underlying value of its investments.
It is unususal for an ETF to declare capital gains at year end. Mututal funds are required to do so. It has to do with their different legal structures.
MTGJR says
I’ve learned Roth is the place to be.
Darr Woods says
Yes, Roths are, but if you are almost 72, like me, and Roths weren’t available until the very end of my IRA funding years, we didn’t have much choice. And a Roth conversion, when you are already hitting IRMAA levels before RMD, are punitive regarding marginal IRMAA and Fed and State taxes. So, my upcoming RMD will be causing me to go into MUCH higher brackets (I guess a nice problem to have). If I had any insight that the stock markets were going to go up so high, increasing my RMD, I would have done small Roth conversions each year starting 10 years ago.
MTGjr says
Definitely a rich person problem. We’re 71 and have been doing conversions for 10 years.
The Wizard says
You are welcome to check the details of VFIAX vs VOO (S&P 500) and VTSAX vs VTI (Total Stock Market).
You’ll find that both the MF and ETF versions have the same dividends and zero CGDs.
I completely agree on the features and advantages of trading ETFs which is why I switched over to them a while back.
If I had the time and inclination, I would track down the distribution details on the few MANAGED ETFs that have appeared recently. I suspect they will be having CGDs in years to come…
The Wizard says
I asked Brave about this; the answer:
Actively managed ETFs are funds where professional managers select assets to outperform a benchmark, rather than passively tracking an index. They generally fall into discretionary (human-driven selection) and systematic (rules-based quantitative) categories.
Top Performers and Popular Choices
JPMorgan Equity Premium Income ETF (JEPI): The largest active ETF by assets, utilizing an options-based strategy to generate income with downside protection.
Dimensional U.S. Core Equity 2 ETF (DFAC): A systematic fund that tilts toward profitability and value factors, holding over 2,300 stocks.
Avantis U.S. Small Cap Value ETF (AVUV): Focuses on small-cap companies with attractive valuations and strong balance sheets.
Roundhill Generative AI & Technology ETF (CHAT): An actively managed tech fund that has significantly outperformed passive indices like the QQQ in recent years.
Capital Group Dividend Value ETF (CGDV): A discretionary fund targeting companies with attractive income potential rather than strict dividend yields.
GeezerGeek says
I also did small Roth conversions before I was in the RMD age range. Now that I’m into the RMDs, what I do every year is a Roth conversion to take me near the top of the IRMAA bracket or a QCD to take me down to the lower bracket. If I’m near the top of the IRMAA b, I do a Roth conversion to near the top and if I’m near the bottom, I do a QCD to below the bottom. Being charitable can save you money.
The Wizard says
At age 76, I do both.
My QCDs give me more headroom to do modest Roth conversions, only around $20,000 the last two years. I’ll determine this year’s conversion size in about a month…
Gary says
We are both age 73 and having been doing Roth Conversions for over 10 years. Our taxes still feel huge, but we continue to do conversions as we attempt to minimize lifetime taxes and maximize our net worth,
We voluntarily push ourselves into the 24% tax bracket with NIIT costs too. Our approach currently spills into another IRMAA bracket. We know that we are paying more than we need to right now, but the long term math says it is not costing us a tremendous amount. However, we think that somewhere along the line, our country will need to fund the deficit problem. We have been diligent in our savings and fortunate with our health and finances, so we are going to be a future target for more taxes, more IRMAA, etc. Our heavy conversions are a partial insurance policy for those future costs (Hey, insurance is not free).
Jim says
Question for Geezergeek: How does that strategy affect your Net Investment Income Tax (NIIT)?
Harry Sit says
My tax calculator for retirees can help you model the effect on NIIT when you have higher IRA distributions from Roth conversion or lower IRA distributions because of QCDs. You can do one round with your baseline, save it, and then increase or decrease the IRA distributions, save it again, and compare with the previous results.
GeezerGeek says
Jim, there’s not much I can do about the NIIT. My combined pension, SS, and investment income puts me over the $250K NIIT threshold so any RMD moves more investment income over the threshold. So basically, my only option is to pay the NIIT, sooner or later. Roth conversions help reduce future RMDs, but the growth of the IRAs has exceeded the amount I’ve converted to Roths, so the RMDs would increase every year, even without the increase in the age factor. I started doing Roth conversions in 2011 but can’t keep up with the growth. Unfortunately, the $250K NIIT threshold doesn’t increase. But all in all, it’s a good problem to have, so I don’t mind paying.
Chuck Wilson says
Thanks so much for this information but I’m confused about on thing? If the most recent information is that the first step up for a married couple is at 224k why is your projection for the next years first step up with a zero percent inflation showing 230k for a married couple instead of the 224k just published am I missing something?
Jeff Enders says
Chuck – Harry explains that above. Look at the chart with the curve up above (the commentary has the gasolene example).